Bank side infrastructure for on chain settlement.
Meridyan enables regulated financial institutions to originate, settle and reconcile payments on blockchain networks from within their existing systems.
The platform is deployed inside the bank's own perimeter and integrates through ISO 20022, so core banking, payment and compliance systems remain unchanged. Meridyan is a software vendor. It does not hold client funds and does not take custody of keys.
Built and operated in the EU · GDPR compliant · ISO 27001 and SOC 2 certification in progress
- Integration
- ISO 20022
- Role
- Software vendor, no custody
- Deployment
- On premise or EU cloud
- Data residency
- EU
Corporate clients already settle in stablecoins.
Today that activity takes place outside the bank.
When a corporate client pays a counterparty in stablecoins, the bank's role is limited to funding a third party account. The conversion, the on chain settlement and the transaction record sit with a non bank provider. The bank retains its compliance obligations but has no visibility of the counterparty and no part in the transaction.
Funds a third party provider
The client transfers fiat from its bank account to a stablecoin service provider it has selected independently.
Converts and settles on chain
The provider performs the conversion, executes the on chain transfer and holds the settlement record.
Receives value on chain
The counterparty is credited on chain. Neither the originating nor the receiving bank holds a record of the transfer.
Holds the client account and carries the outbound AML and sanctions obligations, without visibility of the on chain leg.
Books an incoming credit from the provider, with no view of the original payer or the purpose of the payment.
A settlement layer between the bank's existing systems and blockchain networks.
Meridyan integrates with the bank through ISO 20022, the messaging standard its payment systems already use. Between those systems and the chain, the platform runs the settlement process as a set of named components, each with defined behaviour that the bank's architecture and risk functions can review.
Designed for review by risk, compliance and internal audit.
Meridyan is a software vendor and does not act as custodian. It holds no client funds and no keys. The platform is built so that the controls a bank's second line expects are visible and verifiable.
Structured for third party risk management and DORA.
Meridyan is designed to carry the lowest risk classification a settlement vendor can reasonably hold in a bank's third party register. The following arrangements support that classification.
No custody of assets, keys or funds
Transactions are constructed by Meridyan software running inside the bank's own environment. Meridyan holds no client assets, no keys and no funds. If the service fails, instructions stop being submitted. No assets are stranded.
Manual fallback at all times
The bank can process instructions without Meridyan at any time. Dependence on the platform is limited and reversible.
On premise deployment and source escrow
The platform can be deployed inside the bank's own perimeter. Source code escrow and documented data formats support a tested exit plan.
Subcontractor transparency and audit rights
A subcontractor register, audit and inspection rights, and incident cooperation obligations are provided in line with DORA contractual requirements.
The scope of an in house settlement stack.
Connecting a bank to blockchain networks at production grade requires settlement engineering, network integrations, key management integration, compliance tooling and a specialist team to operate it. Meridyan delivers that layer as software, measured on latency to finality, availability, correctness under partial failure and auditability.
Settlement engineering, chain integrations, key management, compliance tooling and a specialist team, all before the first transaction is processed.
A single ISO 20022 integration, a predictable operating cost, and a stack the bank's second line can review from the start.
Founded by practitioners from regulated financial institutions.
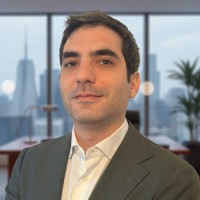
Elie Naba
Responsible for product, commercial development and client delivery. Several years in the blockchain industry building digital asset products for regulated financial institutions.
LinkedIn →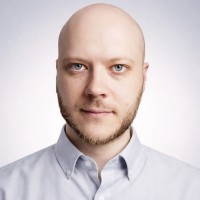
Ivan Ermolaev
Engineer with production experience across payments, KYC and KYB, blockchain and exchange infrastructure, building bank side products for regulated institutions.
LinkedIn →Meridyan is part of the Techstars Future of Finance accelerator powered by ABN AMRO, Amsterdam.
- Program
- Future of Finance
- Cohort
- 2026
- Location
- Amsterdam
Get in touch.
A short conversation to understand the use case, walk through how the platform fits the bank's existing systems, and agree whether a deeper technical session is worthwhile.